You Don’t Need 20% Down to Buy a Chicago Condo. Here’s What You Actually Need
Think you need $60,000 saved before you can buy a $300,000 condo?
You may not.
Qualified buyers can potentially purchase a home with as little as 3% down through certain conventional mortgage programs. Freddie Mac specifically identifies Home Possible® and HomeOne® as options that can allow down payments as low as 3%.
On a $300,000 Chicago condo, that is a major difference.
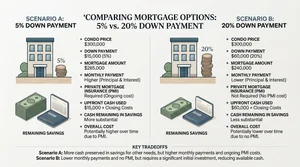
| Down Payment | Cash Amount |
|---|---|
| 3% | $9,000 |
| 5% | $15,000 |
| 10% | $30,000 |
| 20% | $60,000 |
Those numbers are only the down payment. Buyers should also budget for closing costs, property taxes, insurance, HOA expenses and other purchase costs.
Freddie Mac says closing costs commonly run about 2% to 5% of the purchase price, although the actual amount varies by transaction.
So Why Do People Keep Hearing 20%?
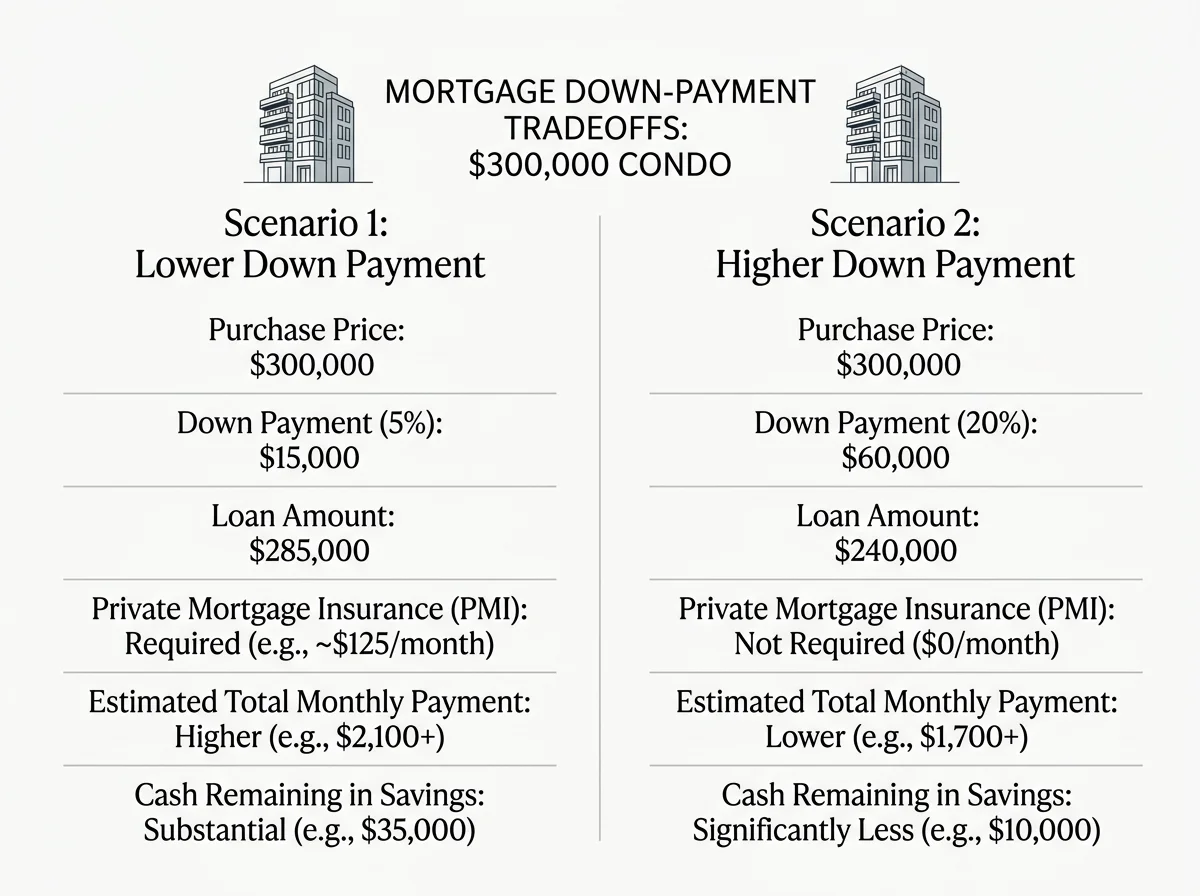
Putting 20% down can have advantages, but it is not a universal requirement to buy a condo.
One major difference is mortgage insurance.
With many conventional mortgages, buyers putting down less than 20% will pay private mortgage insurance, or PMI, which protects the lender if the borrower defaults.
That means the real question is not:
“Can I reach 20% down?”
It is:
“What down payment gives me a monthly payment and cash position I’m comfortable with?”
For some buyers, putting 5% down and keeping more money available for reserves, moving expenses or future repairs may make more sense than draining savings to reach 20%.
For others, a larger down payment could lower the monthly payment and eliminate PMI.
A lender can run both scenarios.
With a Condo, Your Finances Aren’t the Only Thing Being Reviewed
This is where buying a Chicago condo can differ from buying a single-family home.
You may qualify financially, but the condominium project itself also has to meet the lender’s requirements.

Freddie Mac’s condominium guidelines look at factors such as the project’s financial viability, ownership structure and whether the property contains significant commercial or other nonresidential uses.
Lenders may also review issues involving:
HOA finances and reserves
special assessments
major deferred maintenance or critical repairs
insurance
litigation
delinquent HOA assessments
owner occupancy and project characteristics
Freddie Mac specifically notes that documents such as HOA meeting minutes, financial statements and engineering reports may be used when evaluating repairs, deficiencies and special assessments.
That is why getting pre-approved personally does not automatically mean every condo you tour will qualify for the same financing.
The lender is underwriting you and reviewing the building.
Could Illinois Down Payment Assistance Help?
Possibly.
The Illinois Housing Development Authority’s IHDAccess Home program currently offers qualifying first-time buyers assistance equal to 6% of the purchase price, up to $15,000, which can be applied toward a down payment, closing costs or both.
The assistance comes as a 30-year deferred second mortgage with no monthly payment.
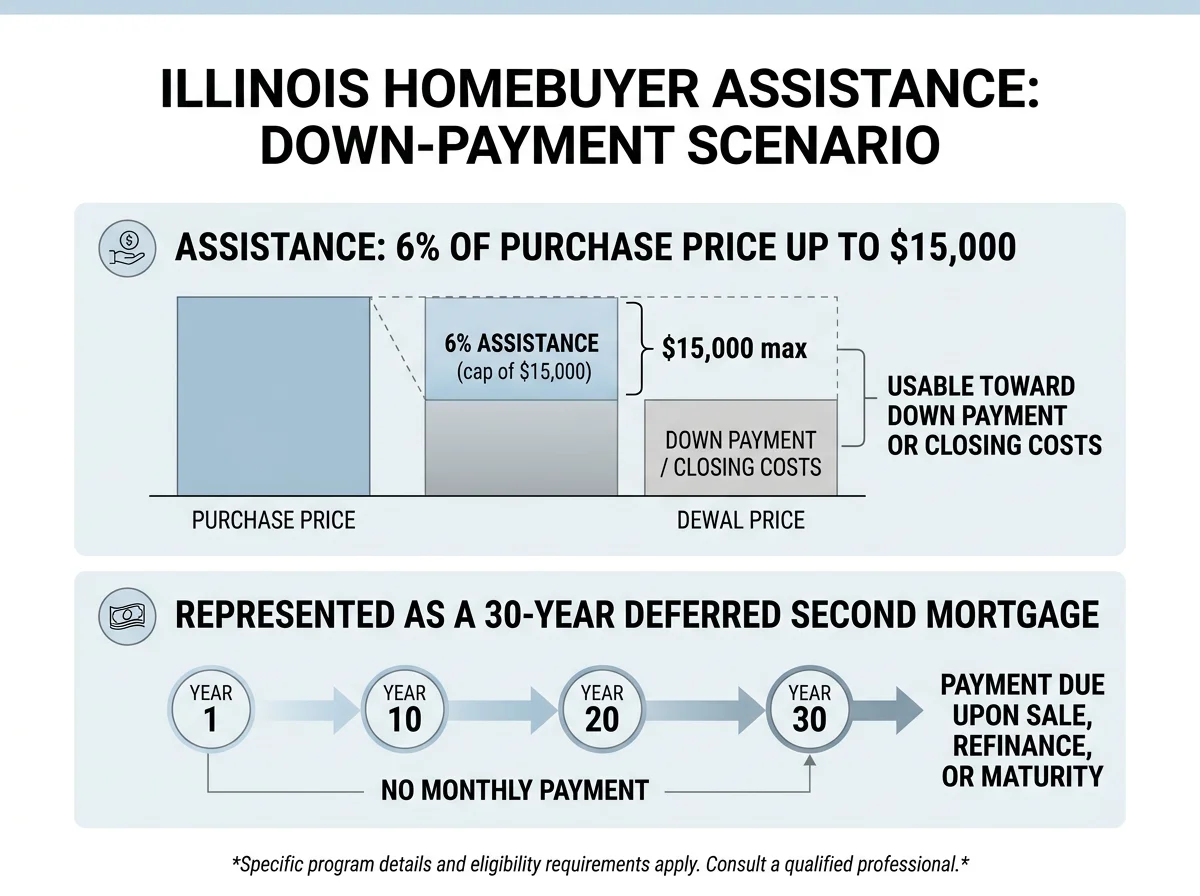
It is not free money. The balance becomes due when the home is sold, the first mortgage is refinanced or the 30-year term ends.
IHDA currently lists limited funds remaining for IHDAccess Home, and funding is not guaranteed until an approved lender completes a reservation. Income limits, purchase-price limits and other program requirements also apply.
Buyers interested in assistance should therefore speak with an IHDA-approved lender early, rather than waiting until they are already under contract.
What Could $300,000 Buy in Chicago?
A $300,000 budget can place buyers into very different condo markets depending on the neighborhood, building and monthly HOA costs.
In areas such as University Village, University Commons and South Loop, buyers may find one-bedroom condos and occasionally larger or more unique options around this range.
In West Loop, the same budget can be more limiting, particularly once parking, assessments and building amenities are considered.
That is why purchase price alone does not tell you whether a condo is affordable.
A $285,000 condo with a $750 monthly HOA could cost more each month than a $310,000 condo with a $350 HOA, depending on financing, taxes and insurance.
For condo buyers, the better comparison is the total monthly housing cost.
Before You Assume You Need Another $50,000 Saved
Talk to a lender.
A renter who believes they need $60,000 for a 20% down payment on a $300,000 condo might discover that a qualifying 5% down scenario requires $15,000 toward the down payment instead.
That does not mean everyone should buy with 3% or 5% down.
It means buyers should understand the options before deciding homeownership is out of reach.
The right starting point is to calculate:
Down payment + estimated closing costs + monthly mortgage + taxes + HOA + insurance + PMI, if applicable.
Then compare that total with your budget and the cash reserves you want left after closing.
Thinking About Buying Your First Chicago Condo?
The Cory Tanzer Group at Option Premier can help you explore available condos in University Village, University Commons, South Loop, West Loop and surrounding Chicago neighborhoods, understand building and ownership costs, and connect with a lender to review financing options.
You may be closer to buying than you think.
The first step is finding out what your actual numbers look like, rather than assuming 20% down is the price of admission.
Stay Connected
Ranked among the top 1% of real estate teams in the Chicagoland market, The Cory Tanzer Group at Option Premier is recognized for proven sales performance, neighborhood expertise, and consistent results across Chicago and the surrounding suburbs.
In the 2026 RealTrends Verified rankings, based on 2025 sales data, the team completed 181 transaction sides representing $79.28 million in sales volume. The Cory Tanzer Group ranked No. 13 in Illinois by transaction sides, No. 20 in Illinois by sales volume, No. 270 nationally by transaction sides, and No. 439 nationally by sales volume.
The team also earned The CARLY, the highest honor for Platinum Sales Dollars and Platinum Units Sold, at the Chicago Association of REALTORS® Sales Awards.
Led by Cory Tanzer, the team helps buyers, sellers, investors, landlords, and renters navigate real estate across Downtown Chicago, the North Shore, and the Western Suburbs, with local expertise in University Village, University Commons, South Loop, West Loop, Little Italy, Pilsen, and surrounding Chicagoland communities.
Connect with The Cory Tanzer Group at Option Premier for trusted local market insight, personalized guidance, and a proven strategy for your next Chicago real estate move.