Buying a Chicago Condo With a High HOA? Here's When the Higher Monthly Fee May Actually Make Sense
A $900 monthly HOA assessment can make a Chicago condo buyer hesitate immediately, especially when another building nearby charges $450.
But the lower number does not automatically mean the second condo is the better deal.
Chicago condo assessments can cover very different things from one building to another. One association may include heat, water, building insurance, staff, a fitness center and substantial contributions to reserves, while another keeps its monthly assessment low but leaves owners paying more expenses individually and potentially facing larger special assessments when major work comes due.
The better question is not simply, “Is this HOA high?”
It is: “What am I getting for this money, and is the association financially prepared for the building's future?”
Start With What the HOA Actually Includes
Two condos with the same purchase price can have very different ownership costs once the monthly assessment is added.
In a full-service Downtown high-rise, the assessment might help pay for professional management, door staff, elevators, common-area utilities, landscaping, snow removal, maintenance, building insurance, amenity spaces and contributions to the association's reserve fund. Some Chicago buildings also include certain utilities, cable or internet packages, although exactly what is covered varies by association.
A smaller walk-up may have a much lower assessment because there is no doorman, pool, fitness center or elaborate common space. That can be a great fit for a buyer who wants fewer services, but it does not automatically mean the building costs less to operate over time.
This is why buyers should compare the total monthly cost of living in each property, not just the HOA line on the listing.
Imagine one condo has a $500 assessment but requires you to separately pay for several utilities, a gym membership and other services you would use anyway. Another charges $800 but bundles some of those costs into the assessment. The second building still has the higher HOA, but the real monthly difference may be much smaller than $300.
There is an important financing consideration too. For mortgage qualification, Fannie Mae includes owners' association dues in the monthly housing expense used by lenders, so a higher assessment can reduce how much a buyer qualifies to borrow even if the fee includes services the buyer considers valuable.
A Higher Assessment Can Be Paying for the Building's Future

One of the most overlooked parts of an HOA assessment is the money that does not provide an obvious amenity today.
Reserves matter.
Illinois condominium law requires association budgets to address reserves for major capital expenditures and deferred maintenance, subject to provisions of the association's governing documents and the statute. In determining appropriate reserves, boards can consider the expected cost and remaining life of major building components, reserve studies and the financial impact of future assessments on owners.
That means part of a higher monthly assessment may be helping prepare for future expenses such as roofs, elevators, masonry, mechanical equipment, windows or other common elements.
Consider two similar buildings.
Building A charges $500 per month but has limited reserves and several expensive projects approaching.
Building B charges $750 but has been consistently contributing toward reserves and completing maintenance before problems become emergencies.
The lower assessment in Building A may look better on the listing page, but a $20,000 special assessment two years after closing can quickly change that calculation.
A higher HOA is therefore not automatically evidence of poor management. In some cases, it can reflect a building that is choosing to collect the cost of long-term ownership gradually instead of postponing it.
The important question is whether the money is being used responsibly.
When a High HOA Should Make You Look More Closely

There is also a major difference between a high assessment that makes sense and one that is high because the building has financial or operational problems.
Buyers should understand why the assessment is at its current level and whether it has been increasing rapidly. Look at the association's budget, reserve balance, recent financial statements and any major capital projects that are planned or already underway.
For resale condos in Illinois, Section 22.1 of the Condominium Property Act allows prospective purchasers to obtain important association information, including anticipated capital expenditures for the current and following two fiscal years, the status of the reserve fund, the association's financial condition, pending litigation and association insurance coverage.
Those documents can put the monthly HOA in context.
A $1,000 assessment in a well-maintained full-service tower with healthy reserves could tell a very different story from a $1,000 assessment in a building that still has major deferred repairs, limited reserves and another special assessment under discussion.
Buyers should also consider whether they will actually use what they are paying for. If the building has a pool, 24-hour door staff, extensive common areas and multiple amenity floors but you do not value any of those features, a less expensive building may fit your lifestyle better even if the first association is financially healthy.
There is no universal “good” HOA number.
The right number depends on the building, the services, the unit, the association's finances and the buyer's priorities.
Compare Buildings by Total Value, Not the Lowest Monthly Fee
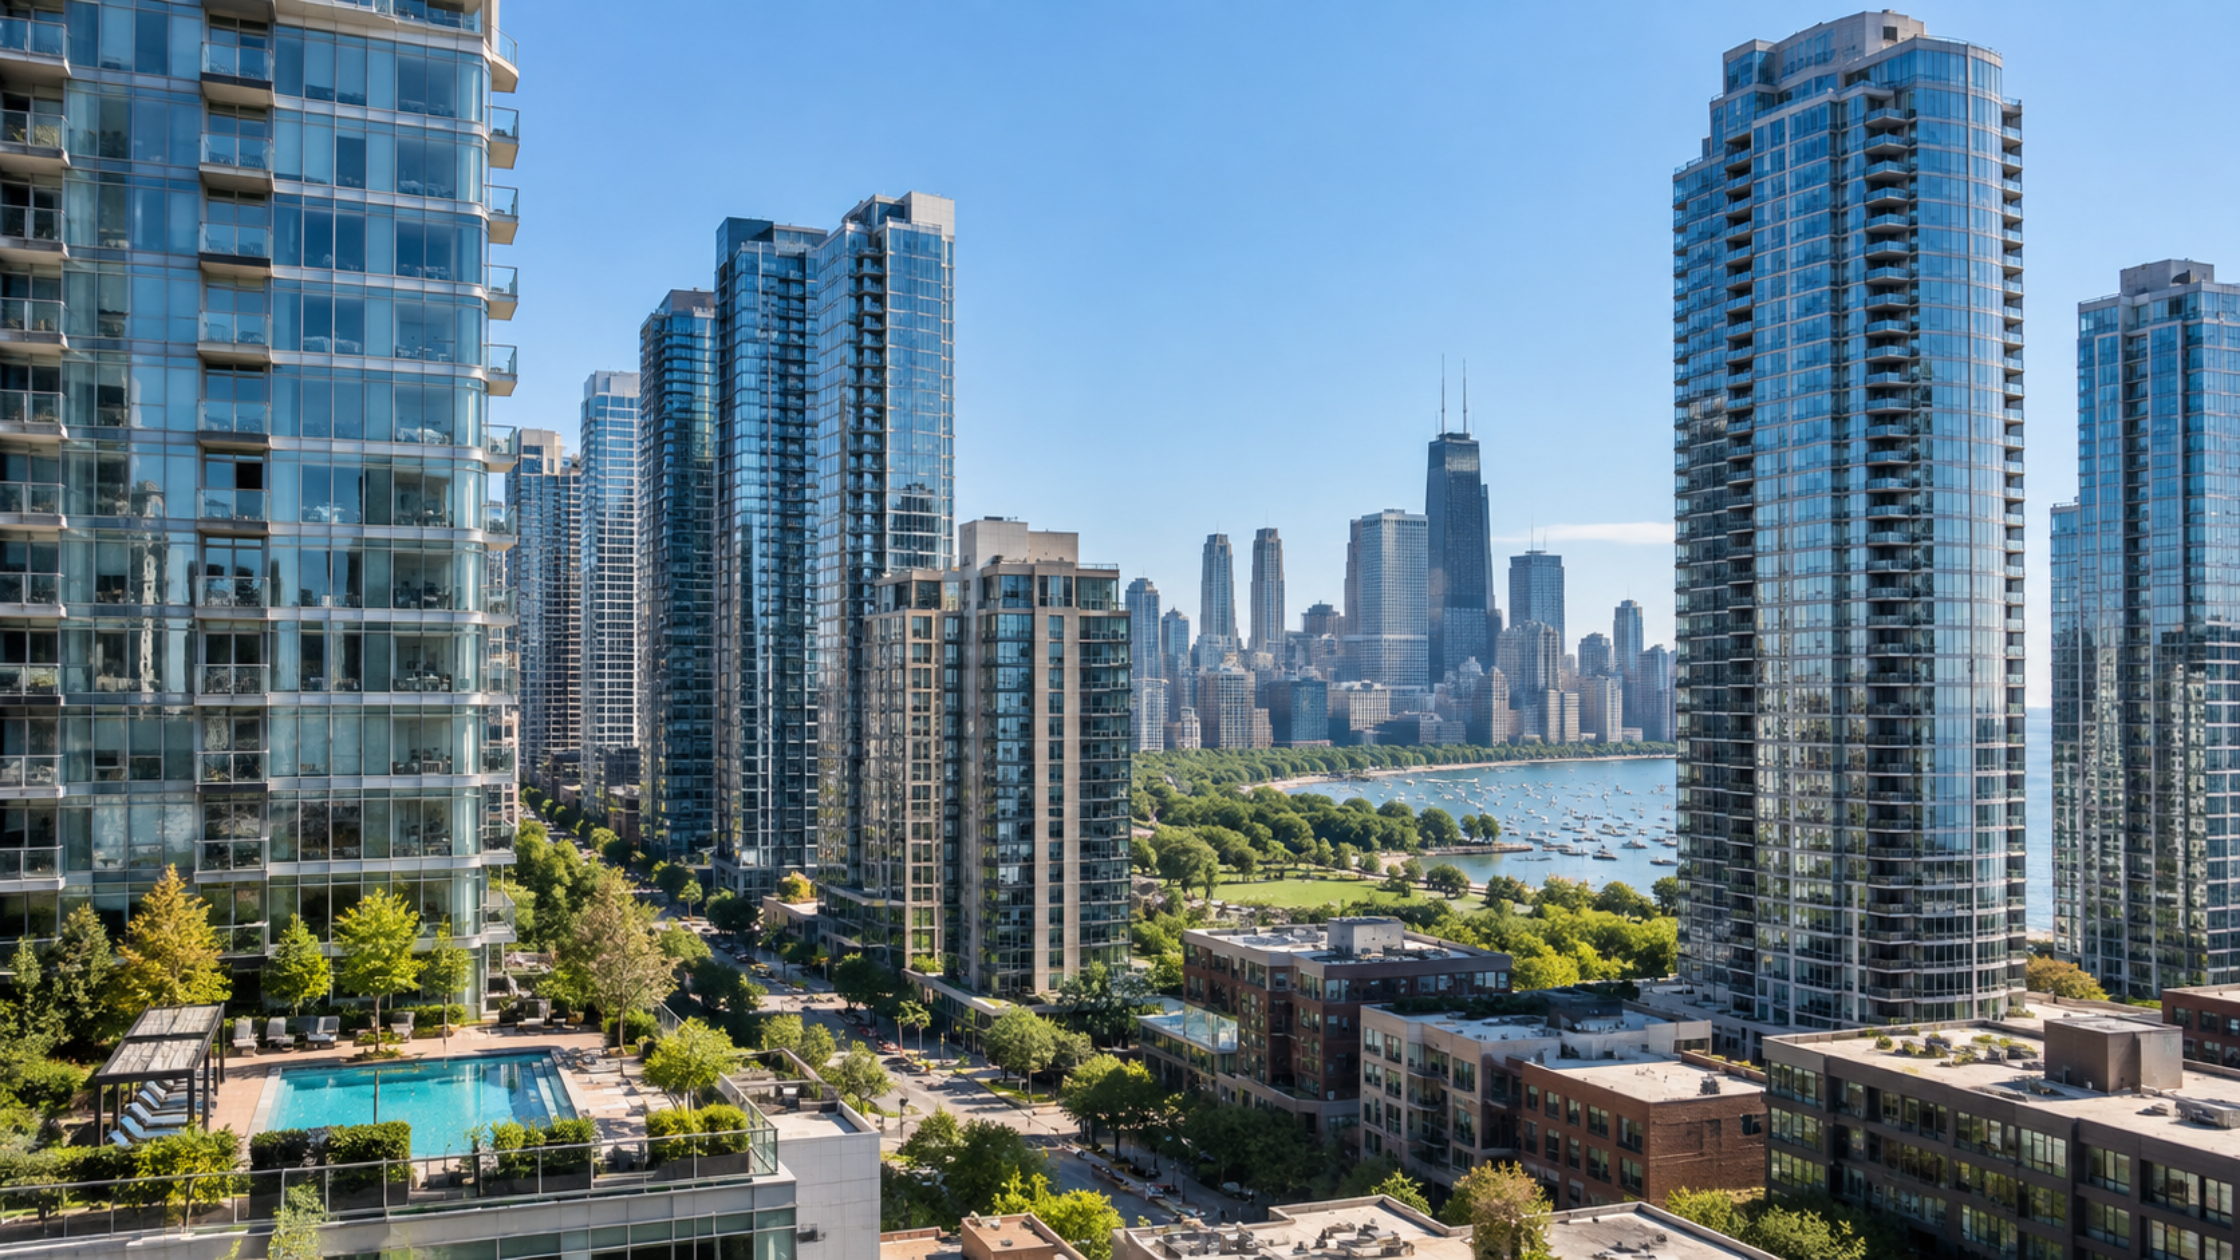
This becomes especially important when comparing Chicago condo-heavy neighborhoods such as South Loop, West Loop, River North, Streeterville, University Village and University Commons.
A buyer might find two similarly priced two-bedroom condos only a few blocks apart with a $400 difference in monthly assessments. Before assuming the lower-assessment building wins, compare what each fee covers, whether parking is included or separately assessed, what the association maintains and how much money is being set aside for future work.
Then look beyond the current year.
Has the association recently completed major projects? Are elevators, roofs, facades or mechanical systems approaching replacement? Is there an active special assessment? Does the association have a professional reserve study? Are assessment increases being used to build reserves, or are operating expenses simply climbing?
Current mortgage rules make the building's financial health relevant to financing as well. Fannie Mae's condominium project standards require lenders to evaluate certain project-level characteristics before many condo loans are eligible, while Freddie Mac's current guidance also addresses replacement reserves, critical repairs and special assessments as part of project review.
That is another reason a buyer should never evaluate a condo solely by the finishes inside the unit.
You are buying into the building too.
So When Does the Higher HOA Actually Make Sense?
A higher assessment can make sense when it covers expenses you would otherwise pay separately, supports services and amenities you genuinely value, maintains the building properly and contributes enough toward future repairs to reduce the risk of financial surprises.
A low HOA can also be completely appropriate, particularly in smaller or simpler buildings with fewer common systems and amenities.
The mistake is assuming lower automatically means better.
When comparing Chicago condos, ask to see what the assessment covers and review the association's financial picture before deciding whether the number is reasonable. A $900 HOA with strong reserves and useful inclusions may ultimately make more sense than a $500 HOA in a building preparing for substantial unfunded work.
The Cory Tanzer Group at Option Premier helps buyers compare Chicago condos at the building level, including HOA assessments, recent sales, parking, amenities, association finances and other factors that can change the true cost of ownership.
The goal should not be to find the Chicago condo with the lowest HOA.
It should be to understand exactly what your monthly assessment is buying.
Condominium finances, mortgage requirements and association documents vary by property. Buyers should review their specific financing with their lender and condominium documents with their Illinois real estate attorney.
Stay Connected
Ranked among the top 1% of real estate teams in the Chicagoland market, The Cory Tanzer Group at Option Premier is recognized for proven sales performance, neighborhood expertise, and consistent results across Chicago and the surrounding suburbs.
In the 2026 RealTrends Verified rankings, based on 2025 sales data, the team completed 181 transaction sides representing $79.28 million in sales volume. The Cory Tanzer Group ranked No. 13 in Illinois by transaction sides, No. 20 in Illinois by sales volume, No. 270 nationally by transaction sides, and No. 439 nationally by sales volume.
The team also earned The CARLY, the highest honor for Platinum Sales Dollars and Platinum Units Sold, at the Chicago Association of REALTORS® Sales Awards.
Led by Cory Tanzer, the team helps buyers, sellers, investors, landlords, and renters navigate real estate across Downtown Chicago, the North Shore, and the Western Suburbs, with local expertise in University Village, University Commons, South Loop, West Loop, Little Italy, Pilsen, and surrounding Chicagoland communities.
Connect with The Cory Tanzer Group at Option Premier for trusted local market insight, personalized guidance, and a proven strategy for your next Chicago real estate move.